
Private shouldn't mean unpriced.
Get access to a liquid pre-IPO listings
Same species, different feathers
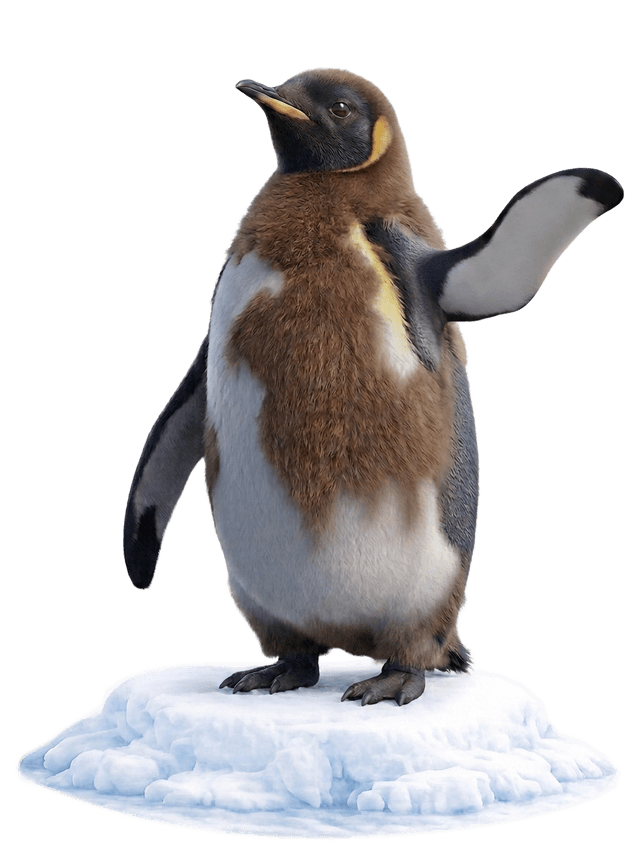
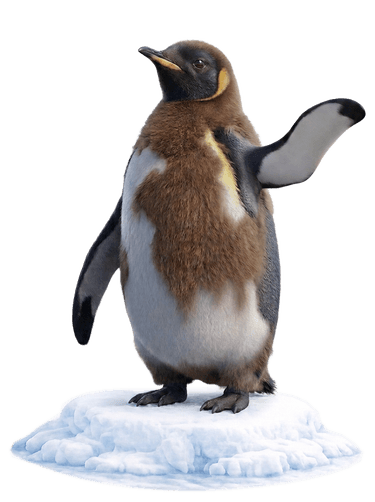
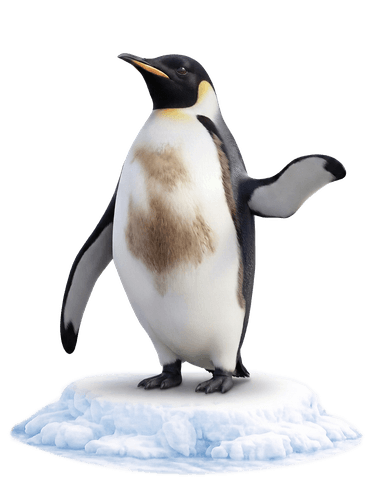
Early naturalists took king penguin chicks for a separate species. They weren't — they simply hadn't changed their feathers. A private company isn't a different kind of company. It's the same kind, before the listing.
Before listing
Private companies ahead of a listing. A price exists only inside closed rounds, and the security changes hands once every few years.
We build the road.
After listing
Listed companies without liquidity. The price is on the screen, but most investors have no way to buy or sell at it. The first issuer on PIPO, XCF Global on Nasdaq, sits here.
We open the door.
Pre-IPO and Post-IPO make PIPO.
One position, through the listing
From a closed round to a public market, your position stays the same. At the listing, only the price reference changes.
- Closed roundToday the shares change hands inside private rounds, and the price lives in the round documents._
- DealsToday the shares change hands inside private rounds, and the price lives in the round documents.Targeted
- MarketToday the shares change hands inside private rounds, and the price lives in the round documents.Targeted, subject to registration
- Listing, if and whenToday the shares change hands inside private rounds, and the price lives in the round documents._
- After listingToday the shares change hands inside private rounds, and the price lives in the round documents.Set per asset
Price reference
latest round + private-market pricing
Price reference: latest round and private-market pricing → exchange price. The method is laid out in each asset's lightpaper: a value on a date, never a forecast.
Where the shares come from, and what we check
Where the shares come from


 token issuer and its SPVToken, one to oneYour approved wallet
The asset is held by the named issuer and its SPV, never by PIPO, and PIPO does not sell securities.
What we check before a private company appears here

The company. Audited accounts and a history we can verify.
The paper trail. Who sells, how they came to hold the shares, whether anything encumbers them, and whether the company's transfer rules allow the sale.
The price. The round documents behind the reference.
The contract. An independent audit before launch, with results in the lightpaper.
Disclosure. What the company commits to report while it is private.
The issuer review is chaired by Igor Lipovetskyi, Founder & CEO
Who it's for
Investors
Private rounds were built for funds. Here, eligible investors apply from a verified wallet.
- business@pipo.vc
Funds and family capital
Blocks on documented terms, handled directly.
- Talk to us
Immutable audit log
Holding shares in a private company? Your security gets access, a price and a second side to the trade.
First pre-IPO companies
IVMS
PRE-IPOTargeted
Delta Zap
PRE-IPOTargeted
7 companies in the pipeline: 2 pre-IPO and 5 post-IPO.
What to weigh
- 01
A listing may never happen, or may happen on terms different from the last round.
- 02
A private company discloses less than a listed one. What it commits to disclose is in its lightpaper.
- 03
The reference is a round valuation, not a live market price, and it can be out of date.
- 04
Before a market opens, the way out depends on the routes set for the asset. Liquidity is never assured.
- 05
You hold a contractual claim on the token issuer, not the share itself.
- 06
Value can fall to zero.
FAQ
Pre-IPO on PIPO is structured exposure to private companies ahead of a listing, through digital notes issued by a named token issuer and its SPV — not by PIPO itself.
You hold a contractual claim on the token issuer (a security token / digital note), not the share of the private company itself. Conversion and exit paths are defined in that deal's documents.
Before listing, the reference is the latest round and private-market pricing. After listing it can move to the exchange price. The method is in each asset's lightpaper: a value on a date, never a forecast.
Secondary trading among approved wallets is targeted where registration allows. Liquidity is never assured; routes are set per asset.
Your position stays the same; only the price reference changes. Conversion or settlement windows follow the deal terms.
Each lightpaper sets what happens on M&A, listing delay, or no listing. Outcomes are contractual, not guaranteed.
Shares can come from the company, employees holding options, or early investors. Sellers and title are checked before a company appears on PIPO.
A separate issuer and SPV ring-fence the asset, keep segregated accounting, and keep PIPO from holding or selling the securities.
Eligibility depends on KYC/AML and geo rules. Only users from supported jurisdictions with an approved wallet can participate.
Possibly. Write to business@pipo.vc — we review transfer rules, title, and whether the company can appear under our issuer structure.
Private shouldn't mean unpriced.
Holding private shares? Talk to us → business@pipo.vc